
Tantan's Event Strategy: A New User Acquisition Model or Costly PR?
Key Points
- •Tantan reported a 90 per cent attendance rate at physical fitness events across Asia-Pacific, alongside a five per cent increase in female sign-ups in subsequent weeks.
- •Jigsaw Dating General Manager Maisie Baker revealed the business runs more than 200 monthly singles events across over 30 US cities using five full-time staff.
- •ATEAM hosted approximately 30 physical events for 2,000 people before launching its digital app product, reversing the traditional go-to-market sequence for dating platforms.
- •Dating apps traditionally operated on gross margins above 70 per cent, but physical events introduce logistics, venue hire, and insurance costs to user acquisition models.
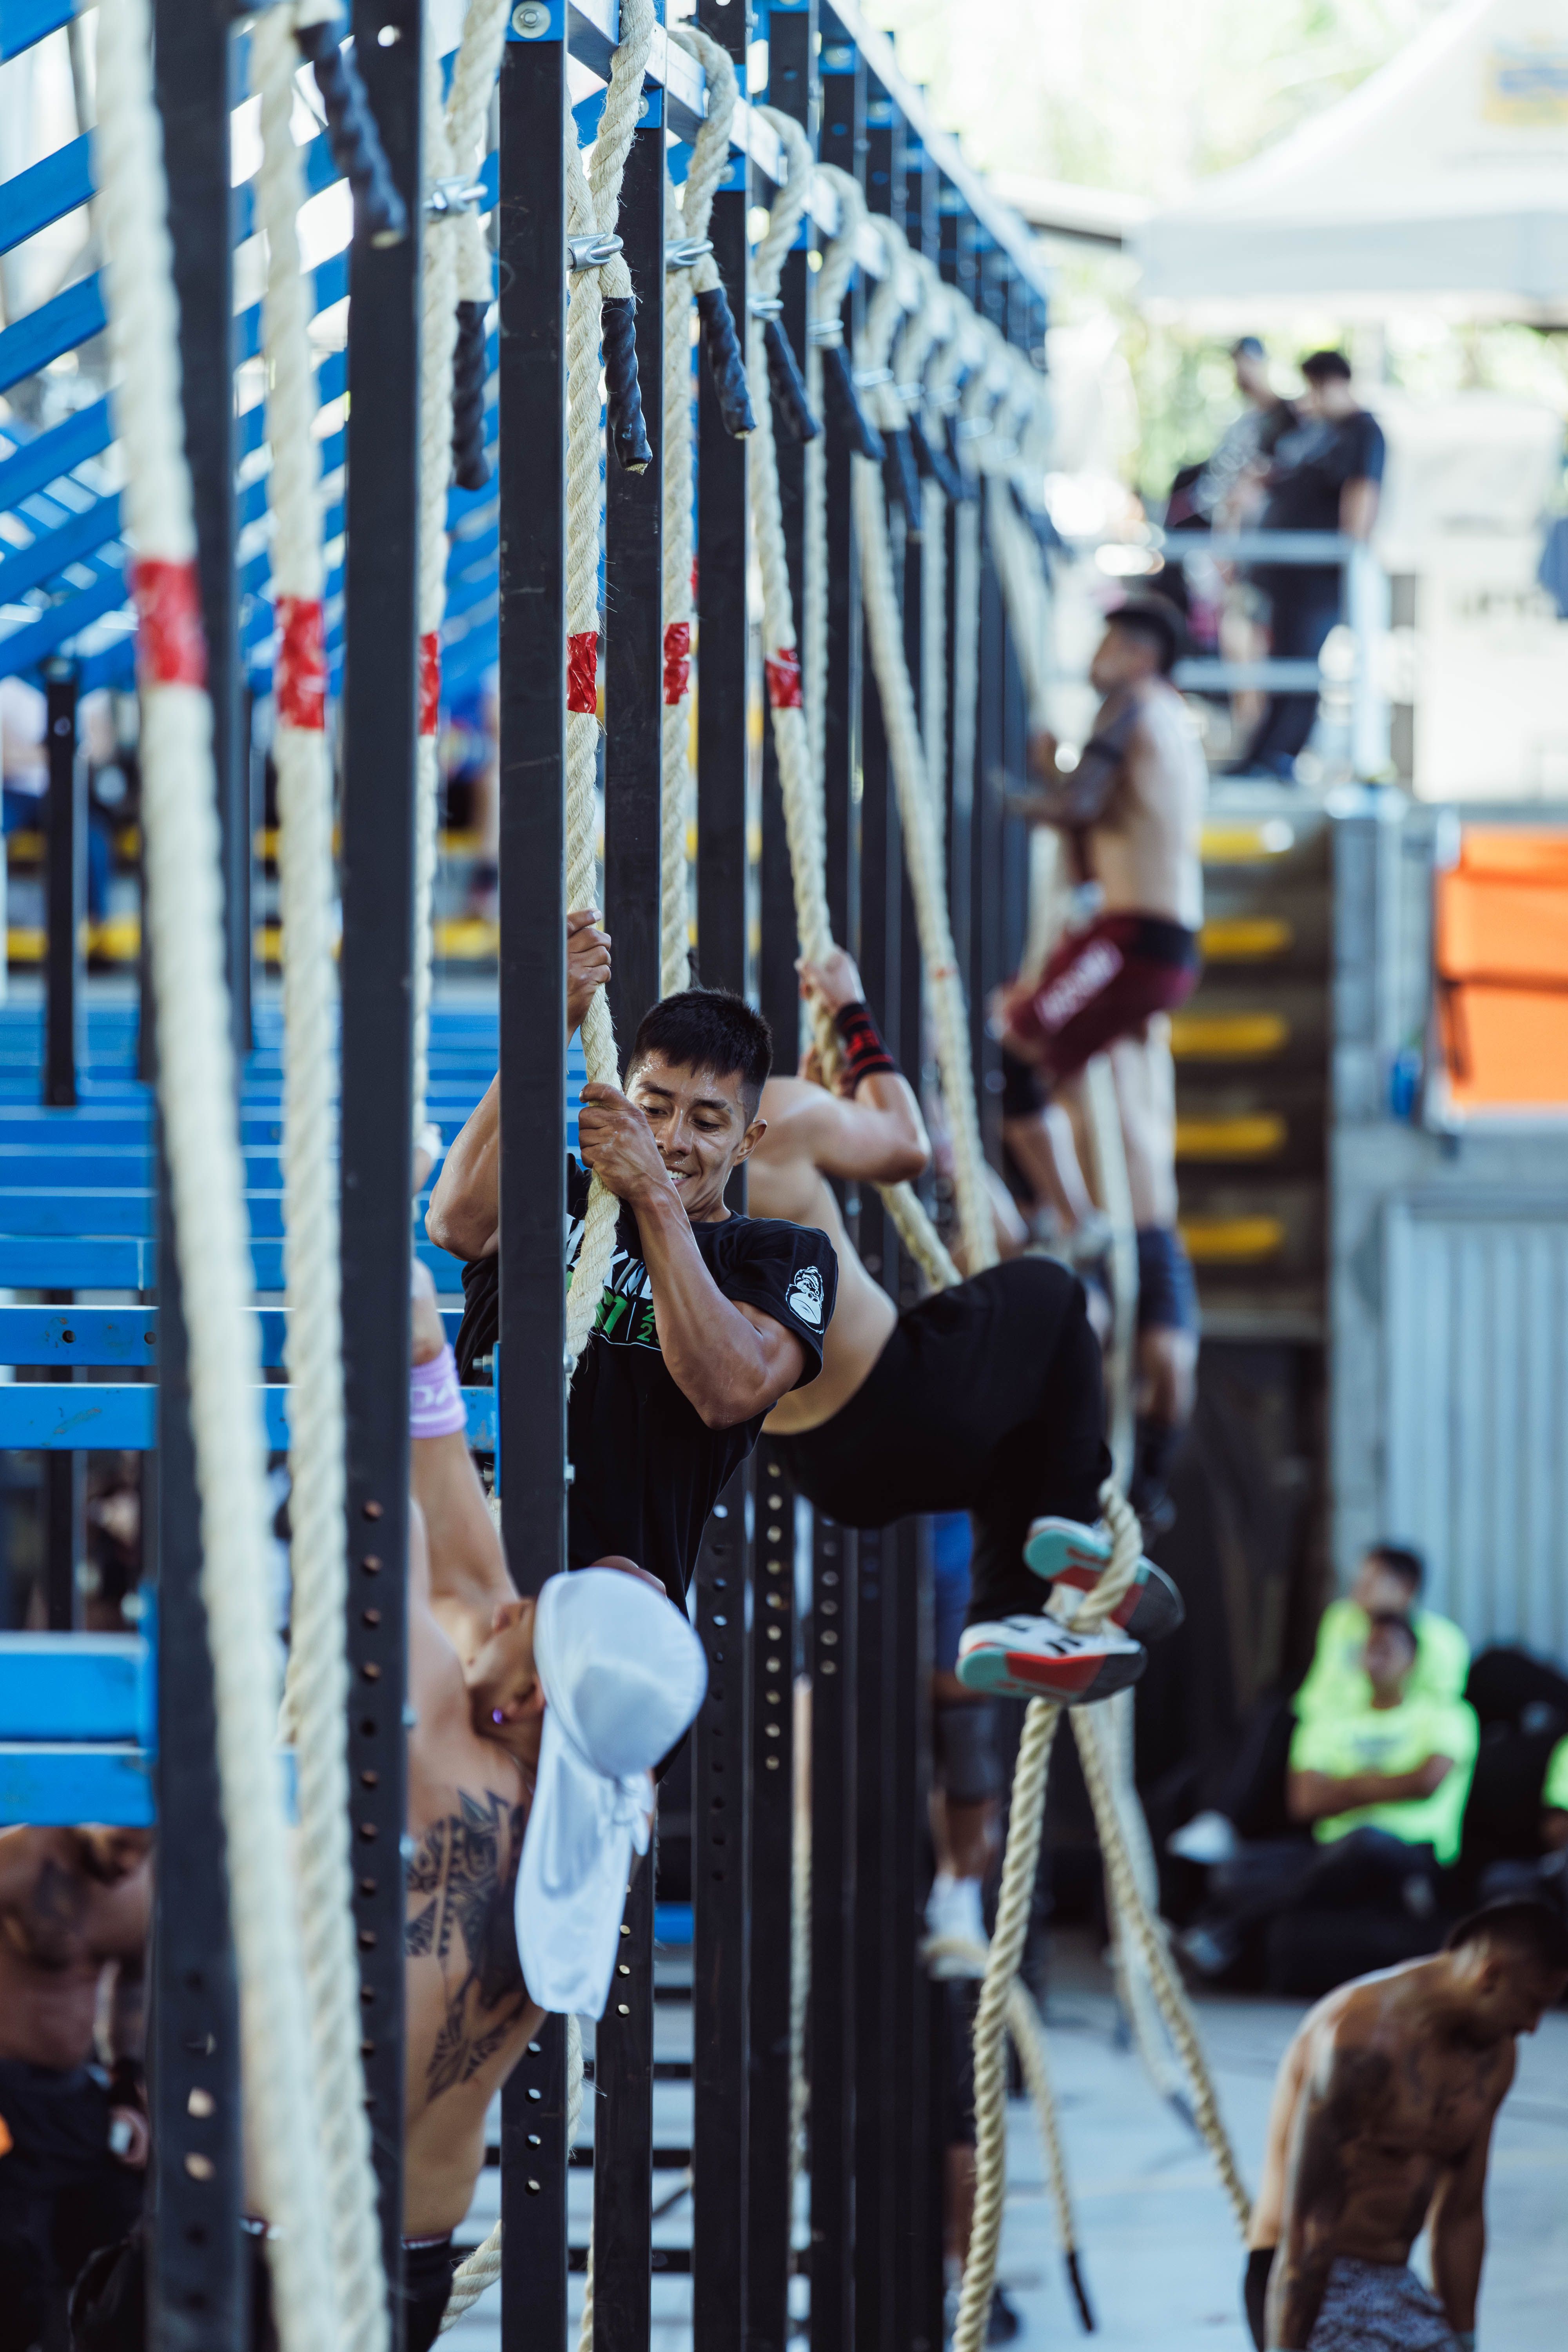
Match Group spent years teaching the industry that dating apps are software margin dreams—zero cost of goods sold, infinite scale, gross margins above 70%. Tantan's latest move suggests the equation may be shifting. The Chinese-owned dating app is doubling down on physical fitness events across Asia-Pacific, and the numbers coming back suggest this isn't a brand exercise—it's a user acquisition channel that may actually work better than performance marketing.
According to figures disclosed by Tantan, approximately 90% of registered participants actually show up to these events, a conversion rate that would make any paid social campaign weep. More importantly for unit economics, the company claims female sign-ups increase by 5% in the week following each event. That's not vanity metric territory when your entire business model depends on maintaining gender balance.
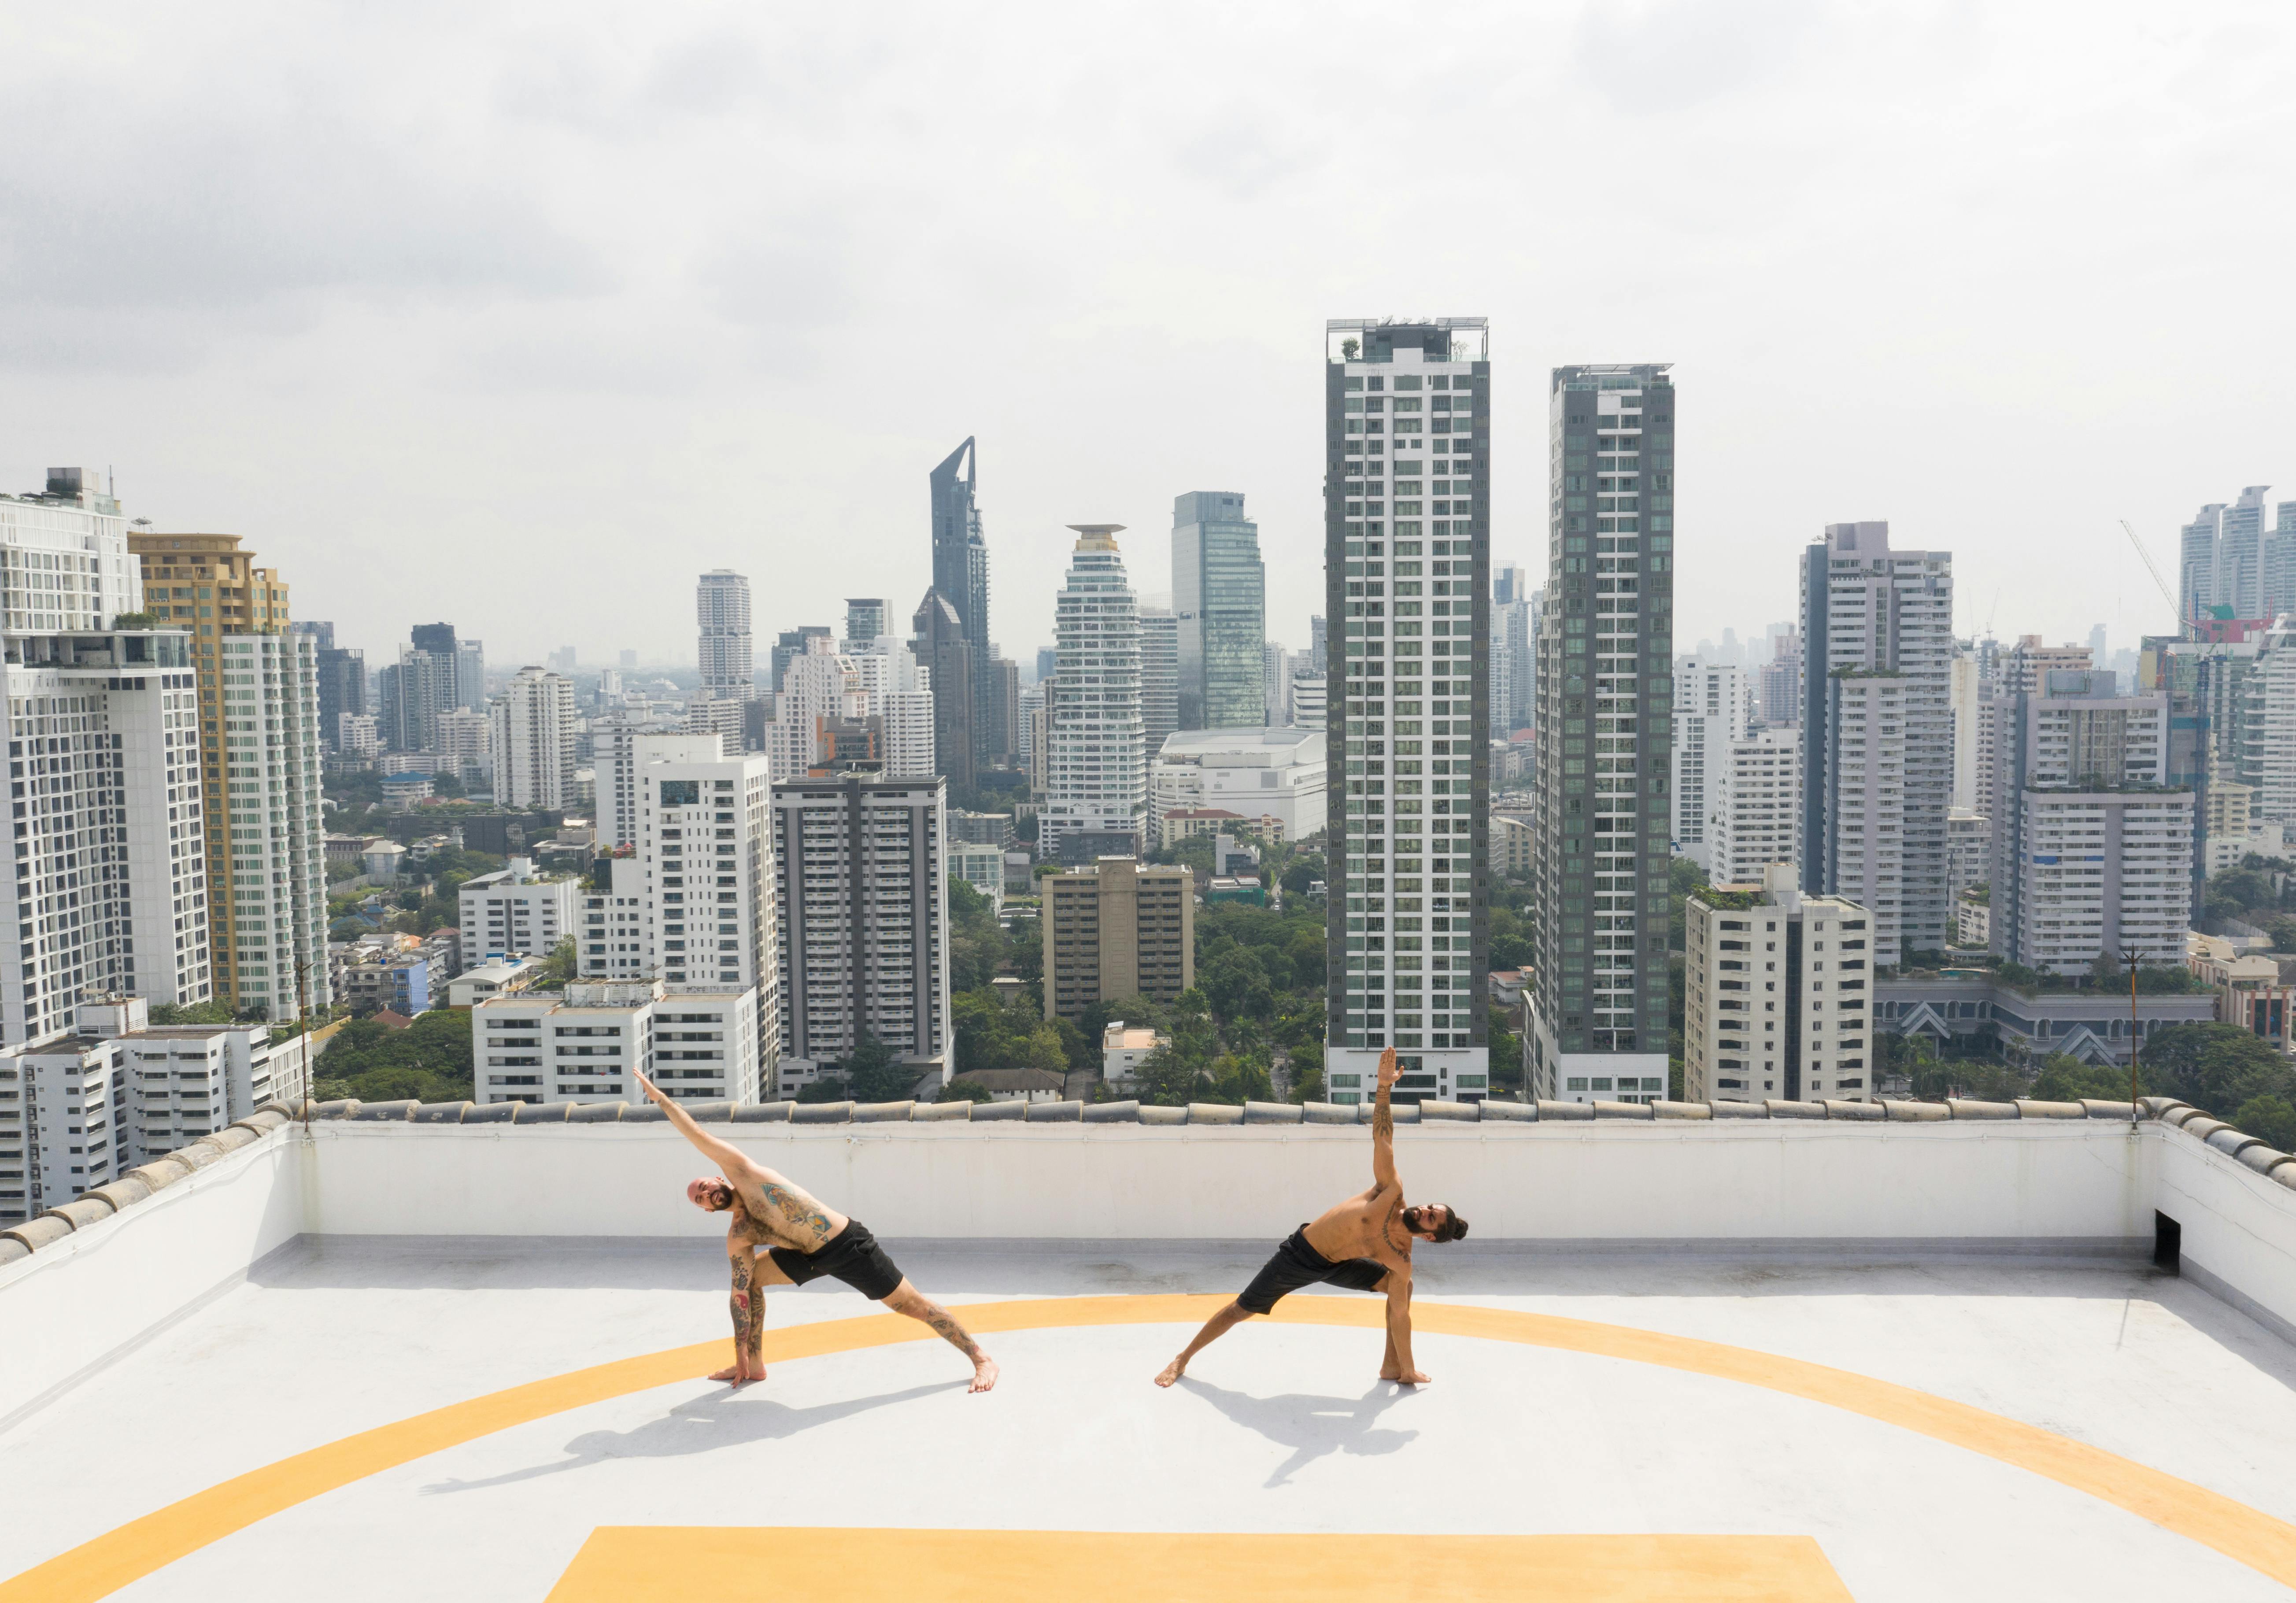
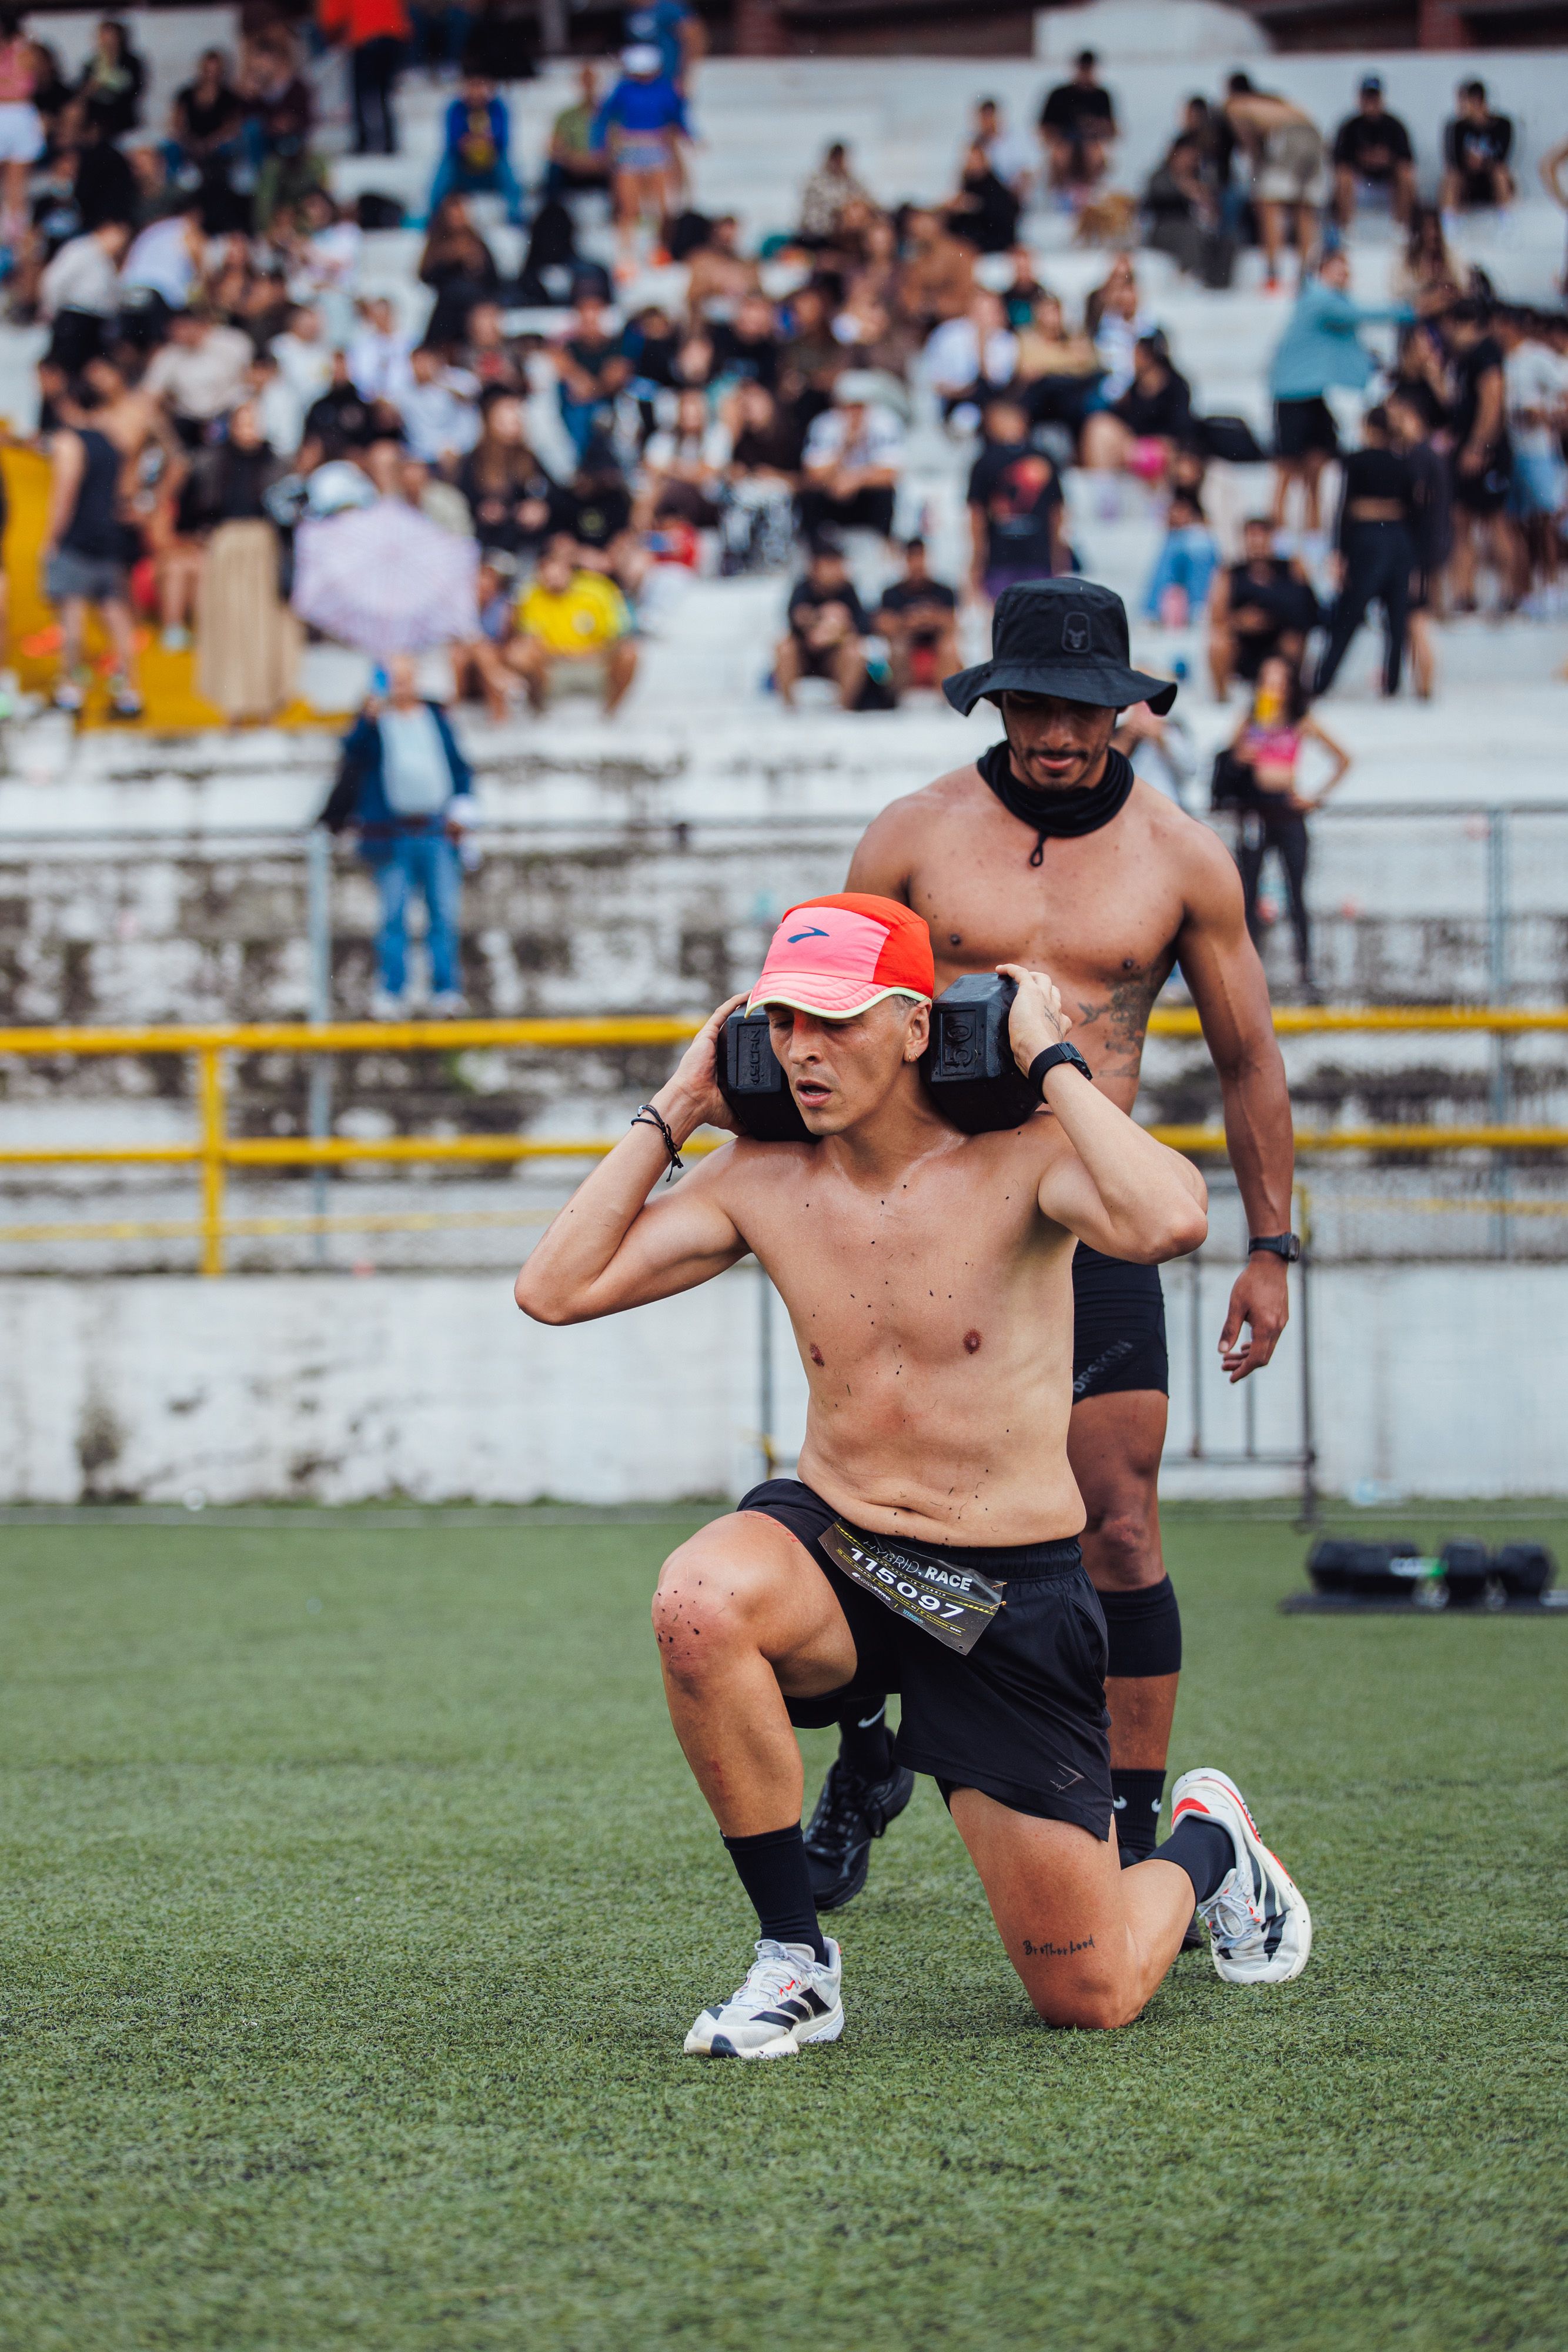
The scale is getting serious. Tantan has a 300-person vertical run planned for Bangkok and a two-day bar crawl in Taichung expecting 3,500 participants. These aren't scrappy pop-ups. They're logistics operations that require permitting, insurance, and the kind of operational muscle dating apps historically haven't needed to build.
Create a free account
Unlock unlimited access and get the weekly briefing delivered to your inbox.
The Industry Moves Beyond Digital-Only
The really interesting data point isn't the 90% attendance rate—it's the 5% female sign-up lift, which suggests events may be solving the gender ratio problem better than any amount of Instagram spend ever has.
The model is spreading faster than anyone expected post-COVID. Surf has partnered with HYROX for pre-race runs and blind date setups. ATEAM, a wellness-focused dating app, ran approximately 30 events for 2,000 people before it even launched its digital product—effectively reversing the traditional go-to-market sequence entirely.
Perhaps most tellingly, at the GDI London Conference, Jigsaw Dating General Manager Maisie Baker disclosed that the company now runs more than 200 singles events monthly across over 30 US cities. The kicker? Jigsaw employs just five full-time staff. That operational efficiency is only possible through a partnership model with third-party event providers—a structure that sidesteps the margin-killing overhead of hiring event coordinators in every metro.
Tinder, meanwhile, is expanding its own real-world events programme through similar third-party arrangements, a tacit admission that even the largest player in the market sees value in getting people off screens.
Why This Model May Actually Work
Dating apps have struggled with three interconnected problems: user fatigue from endless swiping, difficulty attracting and retaining female users, and rising customer acquisition costs as performance marketing channels saturate. Physical events address all three simultaneously.
The 90% attendance figure Tantan reports is worth examining. Free events typically see no-show rates of 40-60%, so either Tantan is charging (which would explain commitment levels) or its brand loyalty in Asia-Pacific markets runs deeper than Western operators might assume. Either way, the conversion from registration to attendance suggests these aren't inflated RSVP numbers—people are genuinely showing up.
The 5% female sign-up increase is the real business case. Dating platforms live or die on gender ratios. When women leave, men follow within weeks. Traditional digital acquisition channels can buy male users all day, but female acquisition costs are typically 3-5x higher and retention is worse. If events preferentially attract women—and early data suggests they do—the unit economics start to look compelling even with higher upfront costs.
There's also a retention angle that's harder to quantify but matters enormously. A user who attends an event has invested time, shown up physically, and likely had at least a marginally positive experience (or they wouldn't have stayed). That psychological commitment is fundamentally different from someone who downloads an app on a whim after seeing an Instagram ad. Early adopters of IRL dating events report being able to assess chemistry and compatibility much faster than through digital interactions.
The Margin Question Nobody's Answering
What nobody's disclosing yet is what these events actually cost per acquired user. A 300-person vertical run in Bangkok requires venue hire, insurance, promotional spend, and staff time. Even with third-party partnerships, someone's paying those bills. If customer acquisition cost through events is comparable to paid digital channels but delivers better retention, the model works. If it's materially higher, this becomes a premium brand-building exercise rather than a scalable growth channel.
Jigsaw's structure offers one possible answer. Five employees supporting 200+ monthly events suggests a radically asset-light model—likely revenue sharing with existing event organisers rather than creating proprietary programming.
The other unanswered question is geographic density. Events work brilliantly in major metros where user concentration justifies the fixed costs. They fall apart quickly in second and third-tier cities where turnout might be 30 people instead of 300. That creates a structural ceiling on total addressable market—precisely the limitation that made software-only dating apps so attractive to investors in the first place.
What Happens When Everyone Does This
If events become table stakes, the competitive advantage disappears and operators are left with higher costs and similar retention rates across the board. The window for differentiation is probably 18-24 months before the playbook gets copied everywhere.
The real test will come when Tantan and others disclose whether users acquired through events have measurably different lifetime value than digitally acquired users. If they do, and if the margin math works at scale, we're watching a genuine business model evolution. If they don't, this is an expensive marketing phase that won't survive the next downturn.
For operators outside Asia-Pacific watching Tantan's experiment, the question isn't whether to try events—it's whether you can afford not to, given what the data is starting to show about female acquisition. And for investors valuing dating platforms on software economics, it may be time to dust off the unit economics models and add a new line item.
Key Takeaways
- •Dating app operators adopting third-party partnership models like Jigsaw Dating can attract female users effectively while mitigating margin-killing operational overhead.
- •Investors must reassess software margin assumptions as real-world events introduce geographic density constraints and higher operational costs in secondary markets.
- •Early movers possess a limited 18 to 24 month window to differentiate through real-world events before competitor copying commoditises the strategy across the industry.
Frequently Asked Questions
Financial Intelligence Desk
The DII Financial Intelligence Desk covers earnings, valuations, funding and the financial performance of the global online dating industry.
Comments
Join the discussion
Industry professionals share insights, challenge assumptions, and connect with peers. Sign in to add your voice.
Your comment is reviewed before publishing. No spam, no self-promotion.