
Tinder's Market Share Plunge: A Swipe Culture Reckoning
Key Points
- •Sensor Tower data shows Tinder's US market share fell to 25%, with Bumble closely trailing at 24% and Hinge reaching 18%.
- •Tinder's global paying subscribers dropped 15% from 11.1 million in Q3 2022 to 9.4 million, despite broader market growth.
- •Bumble's revenue climbed 22% year-on-year to $273.6 million in Q4 2023, whereas Match Group's dating segment grew by 3%.
- •Apple iOS device users account for approximately 80% of global dating app revenue, impacting Match Group's margins as Tinder rankings slide.
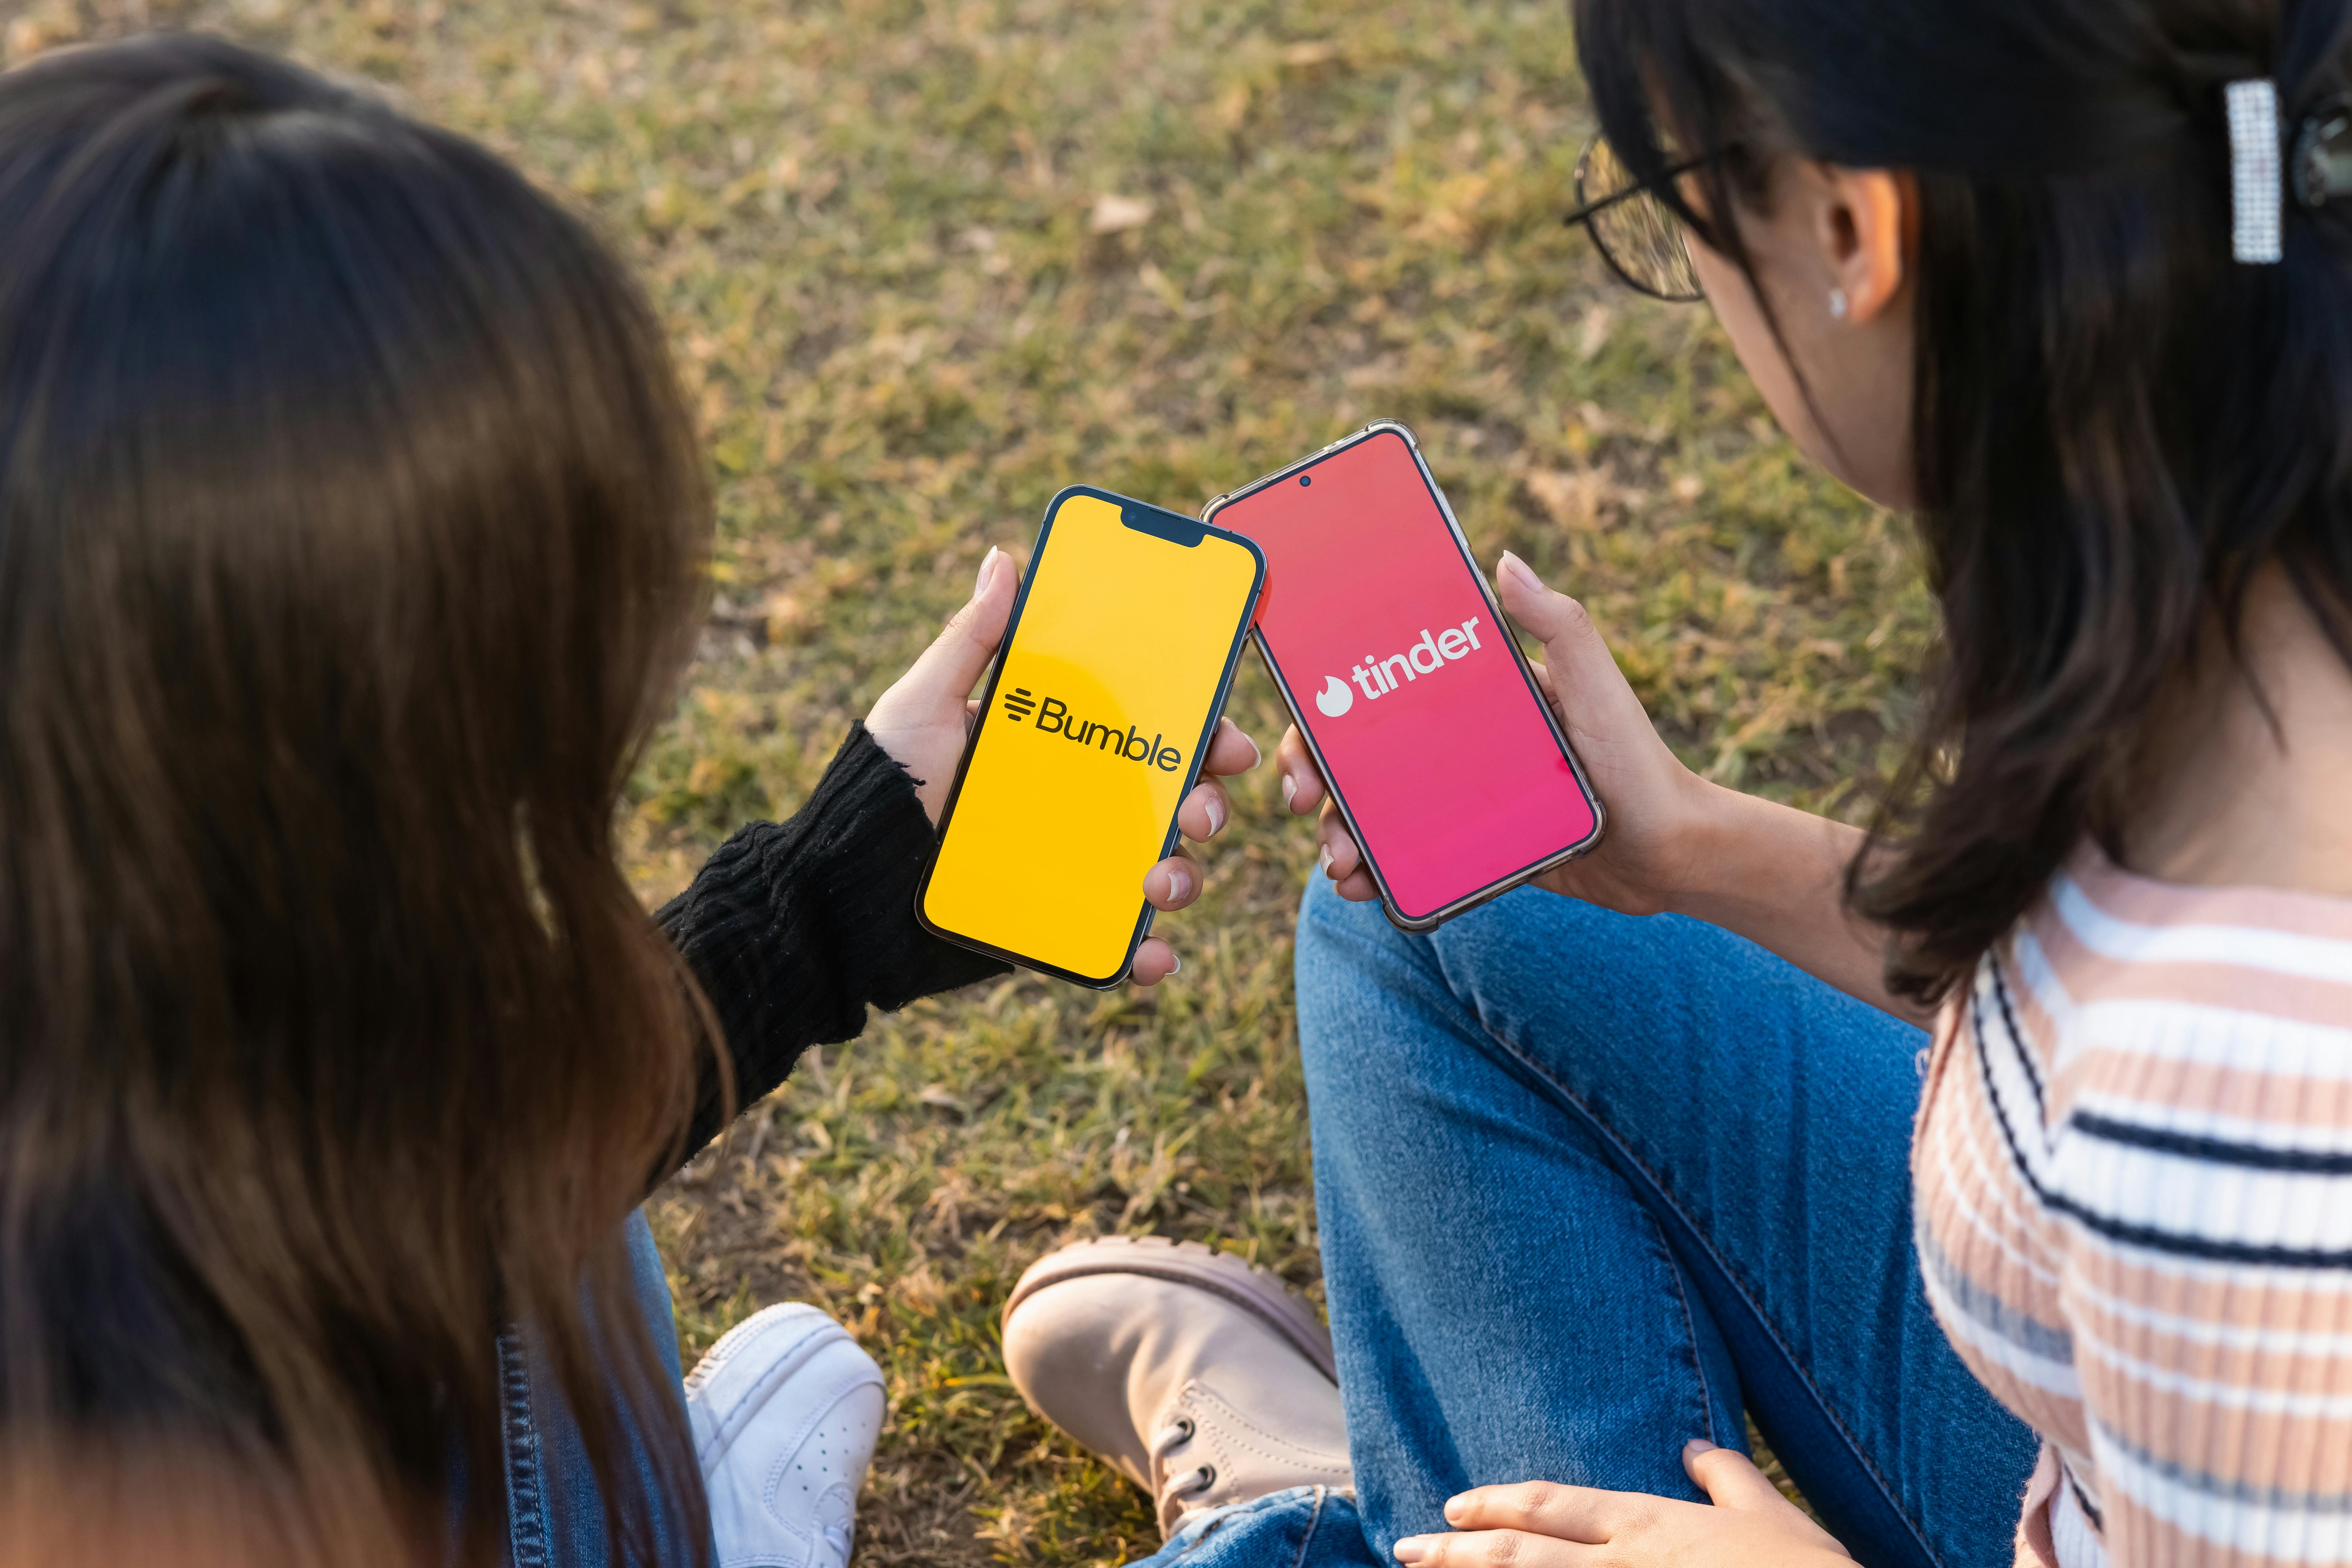
Tinder has surrendered nearly all its lead in the US market, according to fresh data from app intelligence firm Sensor Tower. The platform that once commanded unchallenged dominance now sits at just 25% market share, a mere single percentage point ahead of Bumble. More telling: Tinder's global paying subscriber base has collapsed by 15% since Q3 2022, dropping from 11.1 million to 9.4 million even as the broader dating app market expanded by 15.7% in 2024.
This isn't simple cannibalisation from new entrants. It's abandonment by the users who matter most: paying subscribers willing to commit £10-£30 monthly for premium features. When free users churn, it's noise. When revenue-generating subscribers walk, it's a business model problem.
The End of Swipe Culture's Commercial Viability
Tinder's stumble marks the end of the quick-swipe era's profitability. The platform that invented swipe culture is now being punished for it by users who've realised endless optionality doesn't deliver relationships. What's fascinating isn't that Bumble caught up — it's that users are paying Bumble for features that explicitly limit the chaos Tinder popularised.
Create a free account
Unlock unlimited access and get the weekly briefing delivered to your inbox.
The market has spoken: intentional dating isn't a niche position anymore, it's the mainstream expectation.
The subscriber exodus tells a harsher story than market share alone. Tinder shed 1.7 million paying users during a period when overall dating app revenue grew double digits. These aren't users spreading their spend across multiple platforms or trading down to free tiers elsewhere. They're explicitly choosing to pay competitors instead.
Bumble's revenue climbed 22% year-on-year to $273.6M in Q4 2023, whilst Match Group's (MTCH) dating segment revenue — heavily dependent on Tinder — grew just 3% in the same period. Sensor Tower's figures, based on download and usage data, show Tinder maintaining marginal leadership in only the most technical sense. Hinge, also owned by Match Group, takes third position but has been gaining share faster than either rival, up from 14% in early 2023.
The iOS Premium Problem
Apple device users account for approximately 80% of dating app revenue globally, according to app analytics tracked by Sensor Tower throughout 2024. This concentration creates a brutal competitive dynamic: win on iOS or lose the only users who reliably convert to paid subscriptions. Tinder's App Store ranking has been sliding whilst Bumble and Hinge hold steady in the top-grossing social apps category.

The iOS skew explains why Match Group's dating segment operating margin compressed to 32% in Q4 2023 from 38% a year earlier. When your premium subscriber base shrinks on the platform that generates four-fifths of revenue, you can't offset it by acquiring more Android users. The high-value audience is finite, and they're making deliberate choices about which apps deserve their subscription spend.
Match Group disclosed in its February 2024 earnings call that Tinder's average revenue per user had declined 7% year-on-year, suggesting the platform is discounting aggressively to retain subscribers. CEO Bernard Kim acknowledged 'product and marketing challenges' at Tinder but stopped short of addressing the philosophical shift driving users elsewhere. The company has poured resources into à la carte features — coins, boosts, super likes — but these bolt-ons don't address the core complaint: Tinder optimises for volume, not outcomes.
Portfolio Cannibalisation or Strategic Hedge
Match Group's ownership of both Tinder and Hinge creates an unusual problem. Hinge's 18% US market share represents growth largely at Tinder's expense, confirmed by user research from Pew showing 45% of Hinge users previously used Tinder as their primary app. The parent company is effectively competing against itself, with the newer brand's "designed to be deleted" positioning functioning as an implicit rebuke of its sibling's endless-swiping model.
From a portfolio perspective, this might be strategic diversification. From an operational perspective, it's margin destruction.
Hinge requires different moderation practices, different feature development, and different marketing spend to maintain its "serious relationship" positioning. Tinder's economies of scale — built over a decade of dominance — don't transfer. Match Group is now operating two major platforms with opposing philosophies, serving overlapping user bases, and cannibalising its own highest-margin product.
Bumble (BMBL), meanwhile, faces no such internal conflict. Its entire brand architecture — women message first, photo verification, profile prompts — reinforces a consistent promise of control and intentionality. The company reported 3.2 million paying users in Q4 2023, up 19% year-on-year. Its direct challenge to Tinder isn't feature parity but philosophical opposition: we're not like them, and that's precisely the point.
Friction as a Feature, Not a Bug
The competitive reframing goes beyond marketing. Bumble's product roadmap centres on tools that explicitly slow down the experience — opening moves that require effort, profile badges that signal intentions, AI-powered "compliments" that replace generic openers. These features perform worse in A/B tests for engagement metrics but better for conversion to paid subscriptions.
Users willing to pay want friction that filters intent, not frictionless swiping that maximises volume. Regulatory pressure compounds Tinder's problems. The UK Online Safety Act (OSA) and similar EU frameworks require platforms to verify user identities and moderate harmful content, costs that scale with user volume.
Tinder's massive base — still the largest globally — means disproportionate compliance costs. Smaller, premium-focused rivals like Hinge can spread verification expenses across higher-value subscribers. The regulatory environment now penalises scale without monetisation.
Product Problem or Market Problem?
What comes next depends on whether Match Group treats this as a product problem or a market problem. Product fixes — better algorithms, new features, interface redesigns — assume users still want what Tinder offers but executed better. Market analysis suggests users want something fundamentally different: fewer matches, more intent, outcomes over optionality.
Tinder can optimise its swipe stack all it likes. If the core mechanic no longer aligns with what paying subscribers value, optimisation won't reverse the subscriber decline. The US market share data, whilst striking, understates the global picture.
Tinder retains stronger positions in developing markets where it entered first and competitors followed late. But these markets generate a fraction of the revenue per user that North America and Western Europe deliver. Winning in Lagos whilst losing in London isn't a sustainable trade-off for a public company valued on ARPU growth.
Key Takeaways
- •Dating app operators and investors must pivot towards intentional dating features, as high-spending iOS users actively abandon volume-swiping mechanisms.
- •Match Group faces operational margin compression due to portfolio cannibalisation as Hinge gains market share directly at Tinder's expense.
- •Compliance teams at high-volume dating platforms face escalating costs under frameworks like the UK Online Safety Act without high average revenue per user.
Frequently Asked Questions
Data & Analytics Desk
The DII Data Team maintains the publication's trackers, market data and analytical reference hubs for the online dating industry.
Comments
Join the discussion
Industry professionals share insights, challenge assumptions, and connect with peers. Sign in to add your voice.
Your comment is reviewed before publishing. No spam, no self-promotion.


