
SPARK's Pivot: A White Flag in the Dating App Wars
Key Points
- •SPARK founder Sunny Khurana announced the platform is rebranding from a dating app into a venue-based social network after 12 months of testing in Thailand.
- •During its 12-month test period in Thailand, SPARK facilitated 1,400 venue bookings before deciding to abandon the dating category entirely to focus on group meetups.
- •Early-stage dating startups face tripled user acquisition costs and compliance expenses reaching millions under legislation such as the UK Online Safety Act and EU Digital Services Act.
- •SPARK is adding venue partners and planning an expansion into New Zealand as a low-cost testing market for its reimagined social coordination platform.
When a dating app founder declares the world doesn't need another dating app, he's not making a market observation—he's admitting defeat. SPARK, after a year testing in Thailand, is abandoning romance entirely and rebranding as a venue-based social meetup platform where members organise gatherings without defining whether they're seeking dates, friends, or casual company. Strip away the positioning and what emerges is a retreat from a market where incumbents have made competition functionally impossible for lightly-funded startups.
What 'real-world social network' actually means
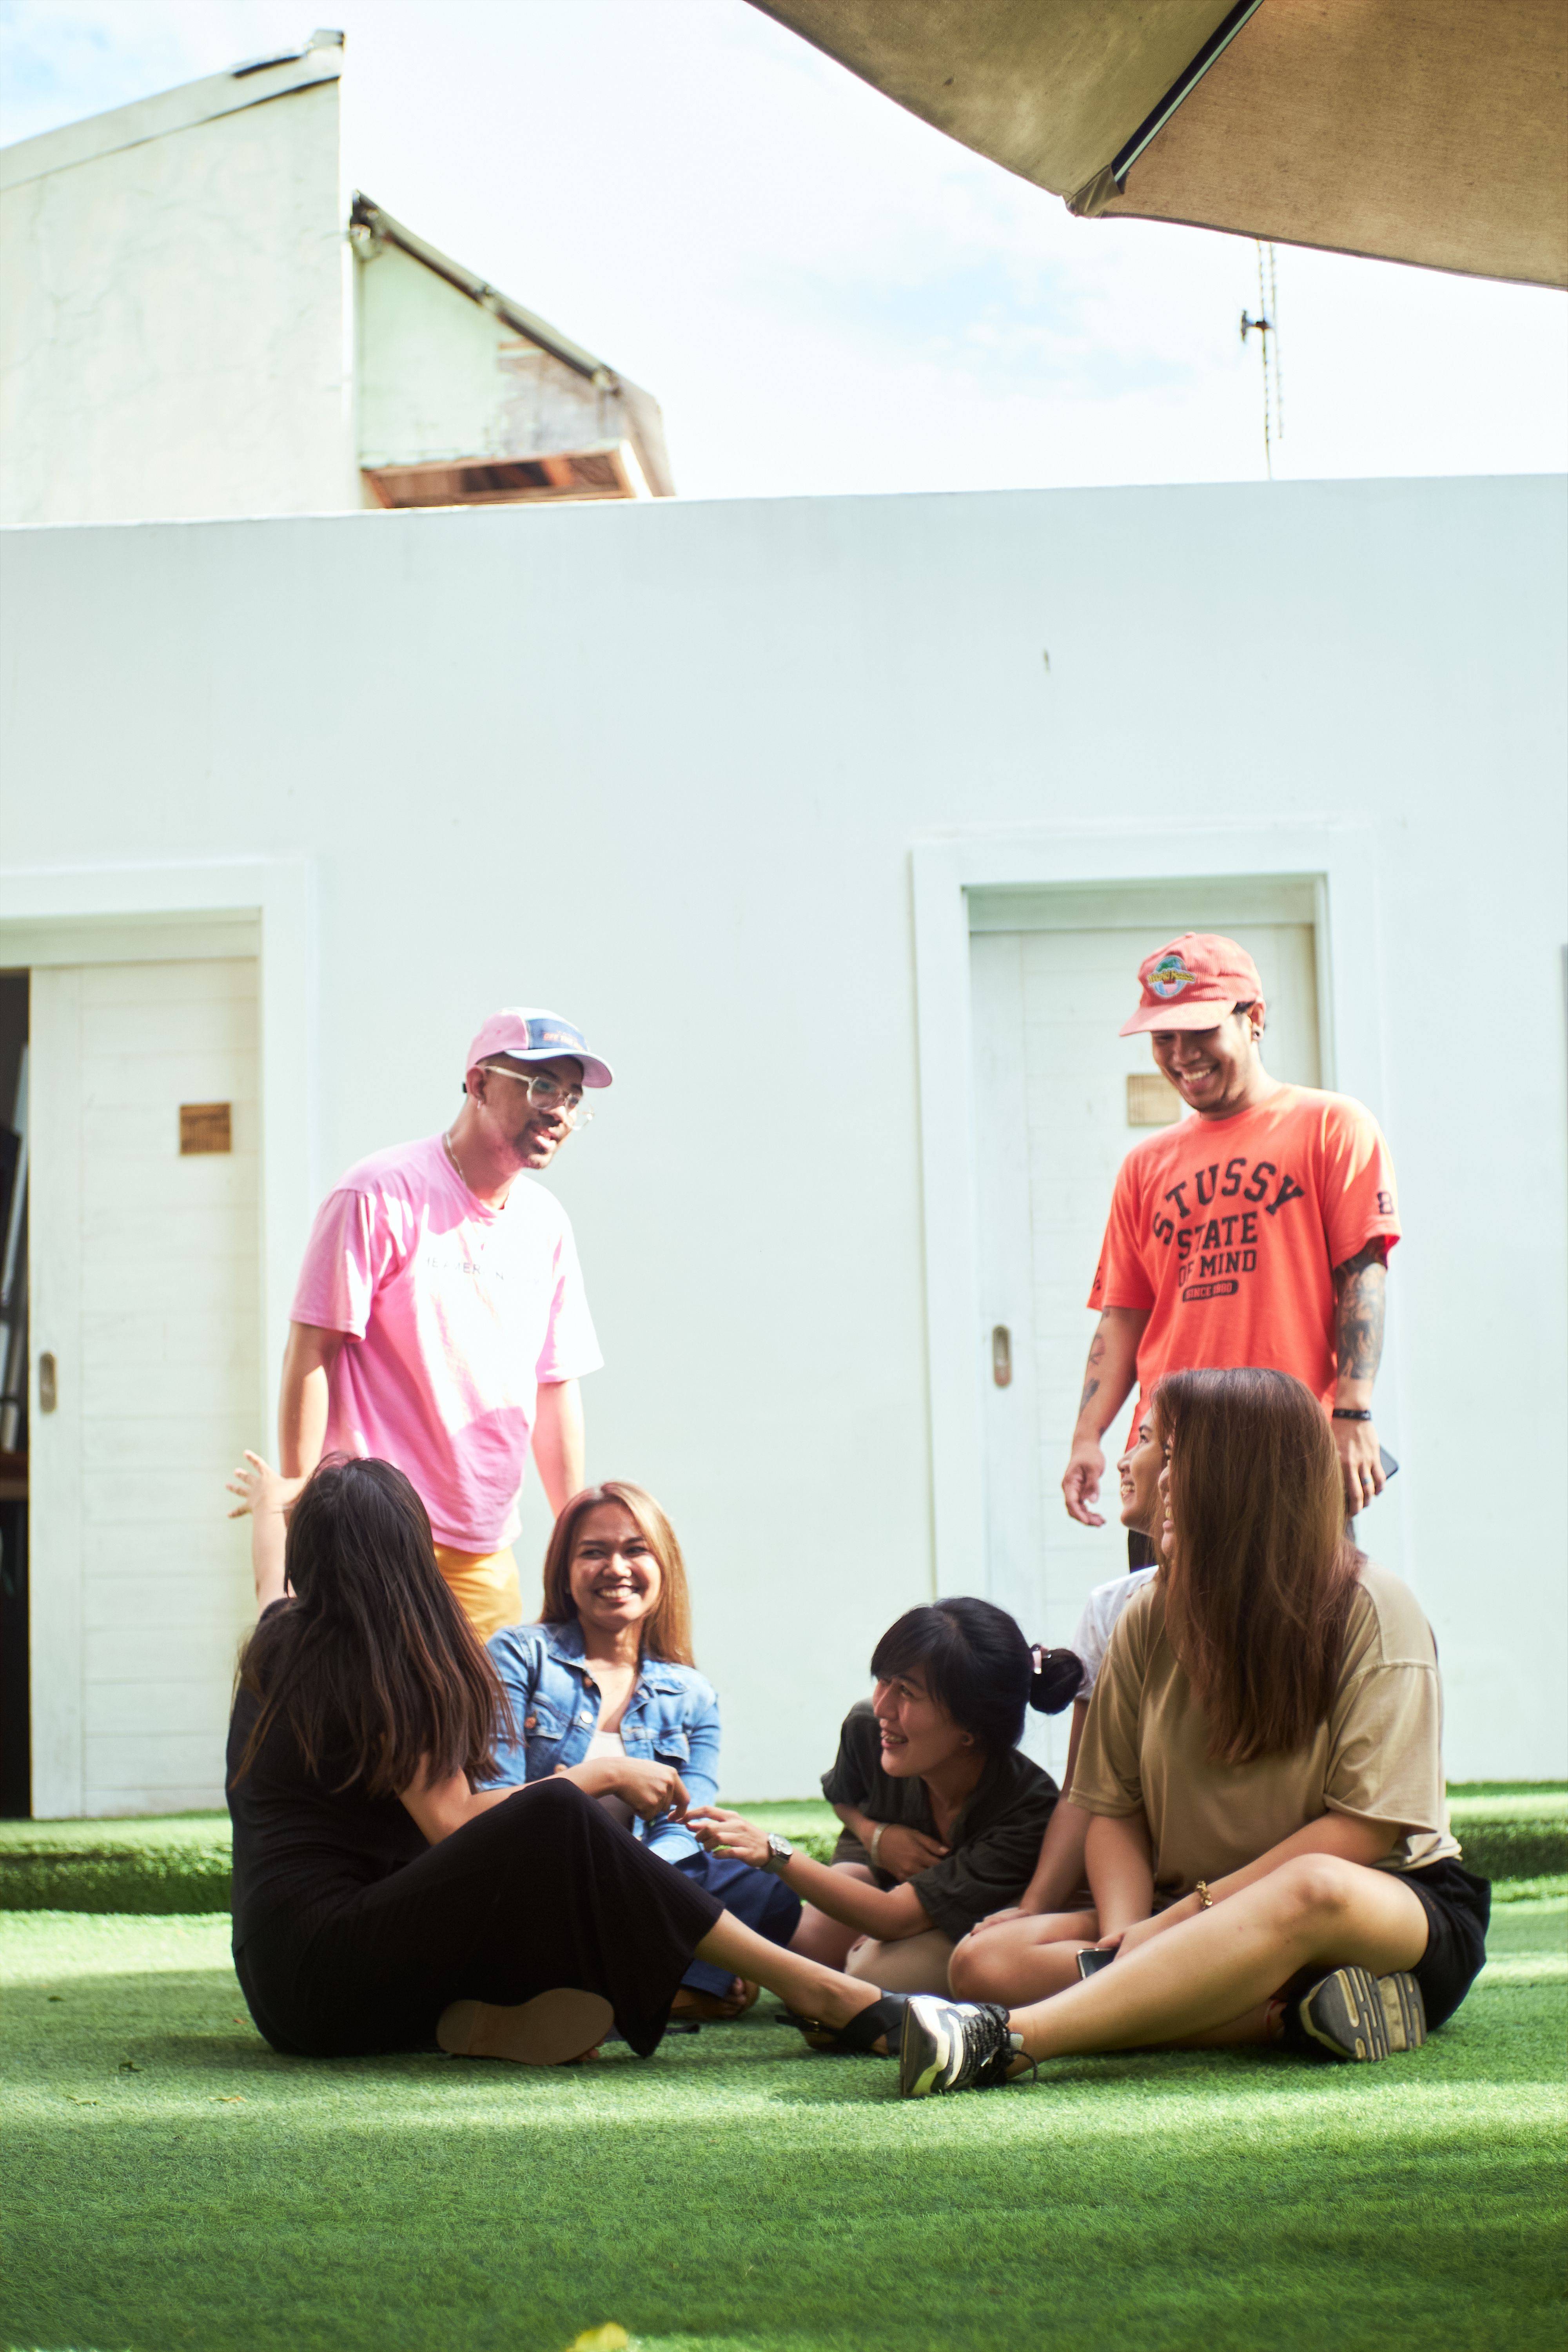
According to Khurana, the reimagined SPARK will let members select a venue, create a plan, and decide who joins. Others can browse those plans and request an invite. The company is building a travel feature that would allow users to book a venue in a city before arrival and assemble a small group to meet there.
The mechanics aren't revolutionary—they describe what Meetup has offered for nearly two decades, with a dash of Bumble For Friends' swipe-to-connect layer. What's notable is the explicit rejection of predefined intent. SPARK won't ask users whether they're seeking dates or mates. Connections emerge from shared activity rather than stated relationship goals.
Create a free account
Unlock unlimited access and get the weekly briefing delivered to your inbox.
That solves a real problem: the pressure and performance anxiety baked into dating profiles. But it creates another. Dating apps have one job—helping singles find romantic partners. When you dilute that into 'helping people meet for unspecified reasons', you're now competing with every social coordination tool, every Facebook group, every WhatsApp thread where someone says 'drinks Thursday?'
The addressable market expands, but so does the competitive set. And your value proposition gets vaguer.
The numbers tell a different story
SPARK facilitated 1,400 venue bookings in Thailand over the past year. The company frames this as traction. Context suggests otherwise.
Even modest dating apps in secondary markets generate thousands of matches daily. If those 1,400 bookings represent SPARK's total marketplace activity after 12 months, the user base is small—likely low single-digit thousands of active members at most. That's not momentum. That's a product struggling to escape the gravity of obscurity.
Khurana told press the pivot follows 'a year of testing and changing the original model'. Translation: the dating version didn't work. Rebranding that as strategic repositioning doesn't change the underlying reality—SPARK couldn't compete as a dating app in a market where incumbents spend hundreds of millions on user acquisition annually and network effects determine winners.
The company is now adding venue partners and preparing to expand into New Zealand. That's a sensible low-cost market for testing before attempting scale. But it also reinforces how early-stage this operation remains.
Dating app fatigue meets the friendship economy
SPARK's exit from dating maps onto two industry threads worth watching. First, operator fatigue with the dating model itself. Bumble launched Bumble For Friends in 2022. Tinder experimented with friend-finding features. Yubo, Hoop, and a dozen other social discovery apps position themselves as alternatives to swipe-based romance.
When dating companies diversify into friendship and social connection, it's partly about expanding addressable markets—but it's also a hedge against declining engagement and user satisfaction in core dating products. Member surveys consistently show frustration with app effectiveness. Operators feel it in retention metrics.
Second, the travel-plus-social opportunity. Platforms like Showaround, Couchsurfing, and Meetup have long targeted visitors seeking local connections. Dating apps have nibbled at this—Tinder Passport, Bumble Travel Mode—but mostly as feature add-ons rather than core positioning.
SPARK is betting that booking a venue and finding a group before arrival solves a genuine pain point for solo travellers. It might. But monetising social coordination is notoriously difficult unless you're taking a cut of the booking or charging for premium access—and the company hasn't disclosed a revenue model.
What this signals about dating's competitive reality
The broader implication isn't about SPARK's specific trajectory. It's what the pivot reveals about barriers to entry in dating. A decade ago, launching a dating app felt plausible. Differentiate on niche, community, or UX. Acquire users through targeted channels. Build network effects city by city. Some succeeded—Hinge, Feeld, The League.
That window has largely closed. Match Group owns the category leaders plus a portfolio of niche brands. Bumble commands the challenger position. The capital required to compete at scale has ballooned.
User acquisition costs have tripled. Member expectations around trust, safety, and moderation have professionalised overnight thanks to regulation like the UK Online Safety Act and the EU Digital Services Act. Compliance infrastructure that would've cost £200K five years ago now requires millions.
For a bootstrapped or lightly-funded startup, competing in dating increasingly means competing for scraps—second-tier markets, hyper-specific niches, or positioning as the anti-app (which is what Khurana is now attempting). Walking away and rebranding as social infrastructure isn't irrational. It's an acknowledgment that the market has matured past the point where another generalist dating app stands a fighting chance.
Whether SPARK's new direction succeeds is almost beside the point. The more interesting question is how many other early-stage dating apps are running the same calculus—and deciding the odds are better elsewhere. As user numbers decline for the first time on major matchmaking platforms, the shift toward real-life interactions over algorithmic matching may represent more than a trend—it could signal a fundamental rethinking of how digital platforms facilitate human connection.
Even established players like Tinder have faced questions about whether they've lost their spark, suggesting the challenges run deeper than any single startup's struggle.
Key Takeaways
- •Early-stage dating app operators are increasingly forced out of romance due to soaring user acquisition costs and dominant marketing spend from Match Group and Bumble.
- •Pivoting to venue-based group coordination allows platforms to sidestep dating profile fatigue, though monetisation remains difficult without clear revenue share from venue bookings or premium subscriptions.
Frequently Asked Questions
Newsroom
The DII Newsroom reports daily breaking news across the global online dating, matchmaking and social discovery industry.
Comments
Join the discussion
Industry professionals share insights, challenge assumptions, and connect with peers. Sign in to add your voice.
Your comment is reviewed before publishing. No spam, no self-promotion.